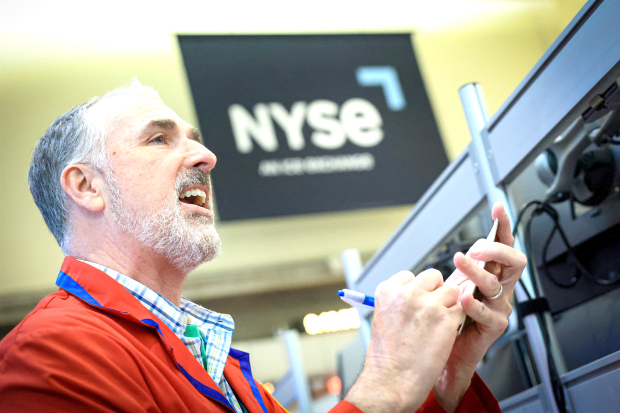
Stocks rebounded yesterday from a rout in technology shares partly driven by concerns about stretched valuations, while the dollar climbed to a one-year peak.
Technology stocks, which were hit hard on Tuesday, edged up ahead of earnings from chipmaker Micron, whose products help power the AI boom. But sentiment remained fragile as investors priced in at least one rate hike from the Federal Reserve this year.
On Wall Street, all three indexes were higher with consumer discretionary, industrials and materials stocks driving gains. Energy stocks were the biggest losers as the continued flow of crude oil through the Strait of Hormuz pushed prices toward four-month lows.
The Dow Jones Industrial Average rose 1.12 per cent, the S&P 500 rose 0.84pc, and the Nasdaq Composite rose 0.89pc.
“We’re probably approaching peak hawkishness in terms of interpreting the Fed’s new stance and it looks like that’s what’s primarily driving asset prices,” said Wasif Latif, chief investment officer at Sarmaya Partners.
“Today, there’s a bit of balance in equities that can be related to the bounce off the pretty meaningful selloff yesterday but also investors are trying to anticipate and position the upcoming earnings announcement from Micron.”
MSCI’s gauge of stocks across the globe rose 0.45pc.
MSCI’s index of Asian equities outside Japan rose 0.15pc. South Korea’s KOSPI gained 3.5pc after dropping 10pc in the prior session.
In Europe, the broader regional stock market was roughly unchanged on the day. A 15pc plunge in shares of defence company Rheinmetall, after media reports of the German government planning to scrap a delayed multi billion euro frigate project, was partly offset by gains in a scattering of heavyweight luxury and tech stocks.
Crude oil prices fell, extending this week’s losses and trading near four-month lows, on signs that more tankers stranded in the Gulf are set to move out of the Strait of Hormuz.
There is a lot of uncertainty about the outlook, given the US and Iran have provided conflicting accounts about what the two countries have agreed as part of their peace deal, including key elements such as nuclear inspections and control of the Strait. Brent fell to $73.53 per barrel, down 4.55pc on the day.
The US dollar rose for a third straight day against a basket of major currencies to its highest in a year as markets anticipate Fed rate hikes.
The euro, however, was one of the main victims of dollar strength, as investors lowered their expectations for the European Central Bank to raise rates much more this year, while pricing in a greater chance that the Fed will lift borrowing costs.
In a note yesterday, analysts at Barclays said their month-end rebalancing model indicated a moderate dollar-buying signal against most major currencies by month-end.
However, the quarter-end model pointed to a strong dollar-selling signal, and “overall, the signal indicates no strong dollar directional bias against all majors at the end of June.”
Markets are pricing in a roughly 32 per cent chance for a rate hike of at least 25 basis points at the Fed’s July meeting, according to CME FedWatch. For September, the chance of a rate rise stands at about 66pc.
