Global bond yields hovered near multi-decade highs yesterday as high oil prices stemming from the Middle East conflict stoked concerns about inflation and rate hikes, while US and European shares found some relief from this week’s lows.
News that the US administration will impose higher tariffs on goods from 60 trading partners also did not help the inflation picture, with 30-year Treasury yields marching towards their highest since 2007 and German 10-year Bund yields – the benchmark for the euro zone – holding close to their highest since 2011.
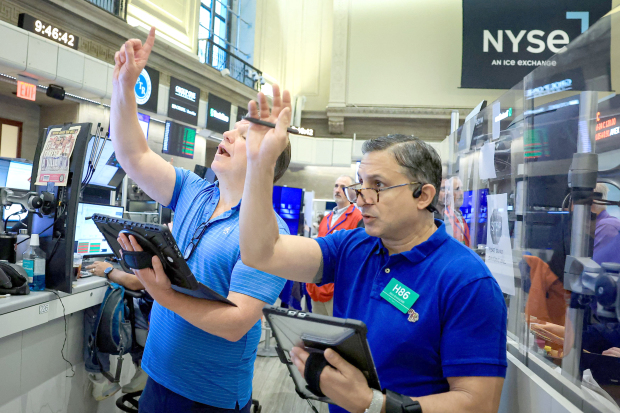
Wall Street stocks were mostly positive, with the Dow Jones Industrial Average up 0.6 per cent, the S&P 500 about 0.5pc higher, and the Nasdaq Composite little changed. Shares of chipmaker Intel fell about 3pc despite bumper results.
Tech stocks have been under pressure this week as investors grow increasingly uneasy about multi-billion-dollar spending on AI that has yet to yield conclusive evidence of paying off.
The pan-European STOXX 600 rose 0.8pc after a more than 1pc drop in the last session, on pace for a mild weekly gain. Brent crude slipped 5pc to $95.71 a barrel, after surging 7pc overnight to a two-month high of $102.
Attacks by Iran-aligned Houthis on Saudi tankers in the Red Sea risk choking off a second crucial Middle East artery for global oil supplies, alongside Iran’s near-closure of the Strait of Hormuz. President Donald Trump threatened “major military punishment” for Iran and its Houthi allies, while the US military conducted a 13th consecutive night of attacks.
“The dollar has been going up for a few days so clearly the risk has been building and the fact that oil has been at these higher levels for several days has really started to work through the cross-asset correlation,” said Shaniel Ramjee, co-head of multi-asset investment at Pictet Asset Management in London.
Markets show traders believe central banks are more likely to raise borrowing costs, with a one-in-three chance of a rate hike from the Fed as soon as next week – a sea change from merely a week ago – while a move in September is more than fully priced in.
The European Central Bank left rates unchanged on Thursday, but a September rate hike is about 70pc priced in. Data yesterday offered a more optimistic economic outlook, after surveys of business activity showed Germany’s private sector returned to growth in July for the first time in four months and contraction in France’s private sector eased this month.
In bond markets, the benchmark 10-year US yield hit a more than 18-month high of 4.713pc, and last traded at 4.671pc. The yield on 30-year bonds was steady at 5.151pc, not far from a 19-year peak of 5.201pc.
“As for the Fed, uncertainty around the outlook for both the policy rate and the balance sheet could weigh on the UST market over the next few months,” John Davies, U.S. rates strategist at Standard Chartered Bank, wrote in a note yesterday.
“Our base case remains an on-hold Fed, but we see a risk that the long-end might start to question whether Chair Warsh is only ready to ‘talk the talk’ rather than ‘walk the walk’ on delivering price stability.”
Precious metals edged higher in choppy trading, with gold up 0.4pc at $4,063 an ounce after falling 2pc the day before, while silver advanced about 1.3pc after a decline of 3.4pc on Thursday.
